

mixetto
mixetto
In order for the media and entertainment industries to thrive, there must be a variety of tools that they can use to create, edit, and manage the content that they seek to convey to the masses. One company dedicated to providing some of this support is Avid Technology (NASDAQ:AVID). In recent years, the revenue picture for the company has been truly lackluster. However, profits and cash flows have shown significant improvement and the near-term outlook for the company is presently positive. From a purely valuation perspective, shares of the enterprise don’t look all that bad either. I wouldn’t go so far as to say that the company warrants tremendous upside. But given an interesting transformation the company is going through and considering that the stock looks reasonably priced, I would rate it a soft ‘buy’ at this time.
For those who aren’t aware of Avid Technology, it’s worth noting that the company describes itself as a developer, marketer, seller, and provider of software and integrations for video and audio content creation, management, and distribution. The company’s primary focus is on catering to the media and entertainment industry with its open platform and comprehensive software tools and workflow solutions. Broadly speaking, the firm’s solutions are used in production and post-production facilities, film studios, cable television stations, recording studios, live sound performance venues, advertising agencies, and other similar organizations. Using its suite of tools, its customers are able to more effectively produce feature films, television programming, news broadcasts, sports productions, and even focus on live events. According to management, the company has been honored for technological innovation with 18 Emmy Awards, one Grammy Award, two Oscars, and the America Cinema Editors Technical Excellence Award.
Of course, this is all just headline information. To truly understand the company, we should dig a bit deeper into its business model. First and foremost, we have what management calls its Creative Software Solutions. This side of the business includes a variety of various tools. One example would be Media Composer, which is used to edit video content like television programming, commercials, and films. Another feature is called Pro Tools, and it operates as a digital audio workstation software that facilitates the audio production process for its customers. This particular platform supports both internally developed and 3rd party software plugins and integrated hardware. Next, we have Sibelius. This product allows users to create, edit, and publish musical scores. It’s used by composers, arrangers, and other professionals in the music space. It’s also used by students and other parties. And finally, we have Avid Link, which is a free desktop and mobile application that offers its creative community the ability to find, network, connect with, and engage in collaboration with others who are interested in artistic pursuits.
Next to mine, we have the Enterprise Software Solutions portion of the business. This is based on the company’s MediaCentral platform and utilizes a suite of applications, modules, and services in order to cater to clients in this space. It also involves SaaS Solutions, which is a strategic partnership with Microsoft (MSFT) to deliver Azure-certified solutions to support end-to-end hybrid and cloud deployments of news workflows. Add lastly, we have various offerings under the Integrated Solutions banner, such as Avid NEXIS, Avid S6, Live Sound, and others. These focus on a variety of features like shared storage, mixing and editing functionality, console systems for mixing audio for live sound reinforcement for live venues, and even production graphics solutions. Outside of all of these features, the company also provides maintenance contracts for its software and integrated solutions, professional services teams that help to deliver workflow design and consulting, learning services teams that deliver public and private training classes associated with this space, and more.

Author – SEC EDGAR Data
Author – SEC EDGAR Data
Over the past few years, the revenue picture for Avid Technology has been anything but great. Between 2017 and 2019, revenue fell slightly, dropping from $419 million to $411.8 million. Then, in 2020, revenue plunged to $360.5 million because of the COVID-19 pandemic. Fortunately, this decline was short-lived, with sales climbing back up to $409.9 million in 2021. Excluding the pandemic-related decline, this does show that revenue has remained in a fairly narrow range. But the downward trajectory of it is slightly disconcerting. In recent years, this decline in revenue has been driven largely by a drop in the Integrated Solutions portion of the enterprise. Maintenance revenues have remained within a fairly narrow range. The real winner for the company, then, has been the subscription side of things. Revenue there rose from 11% of total sales in 2019 to 26.4% of sales last year. To put this in perspective, this category of sales increased from $45.2 million in 2019 to $108.4 million last year. Management attributed this increase to new customers adopting its solutions and customers transitioning from its perpetual product licenses to its subscription-based model. This is a trend that management expects to continue moving forward.
On the bottom line, the picture for the company has been quite impressive. The company went from generating a net loss of $13.6 million in 2017 to generating a net profit of $41.4 million last year. This makes sense when you consider that the subscription line of offerings it’s far more profitable than the company’s other offerings. In 2021, for instance, subscription revenues brought with them an 86.2% gross margin. This compares to 81.2% for maintenance products and 40.7% for all other portions of the enterprise. As net income rose, other profitability metrics followed suit. Operating cash flow increased from $8.9 million in 2017 to $62.5 million in 2021. Meanwhile, EBITDA for the company also increased, climbing from $48.4 million to $75.5 million over the same window of time.

Author – SEC EDGAR Data
Author – SEC EDGAR Data
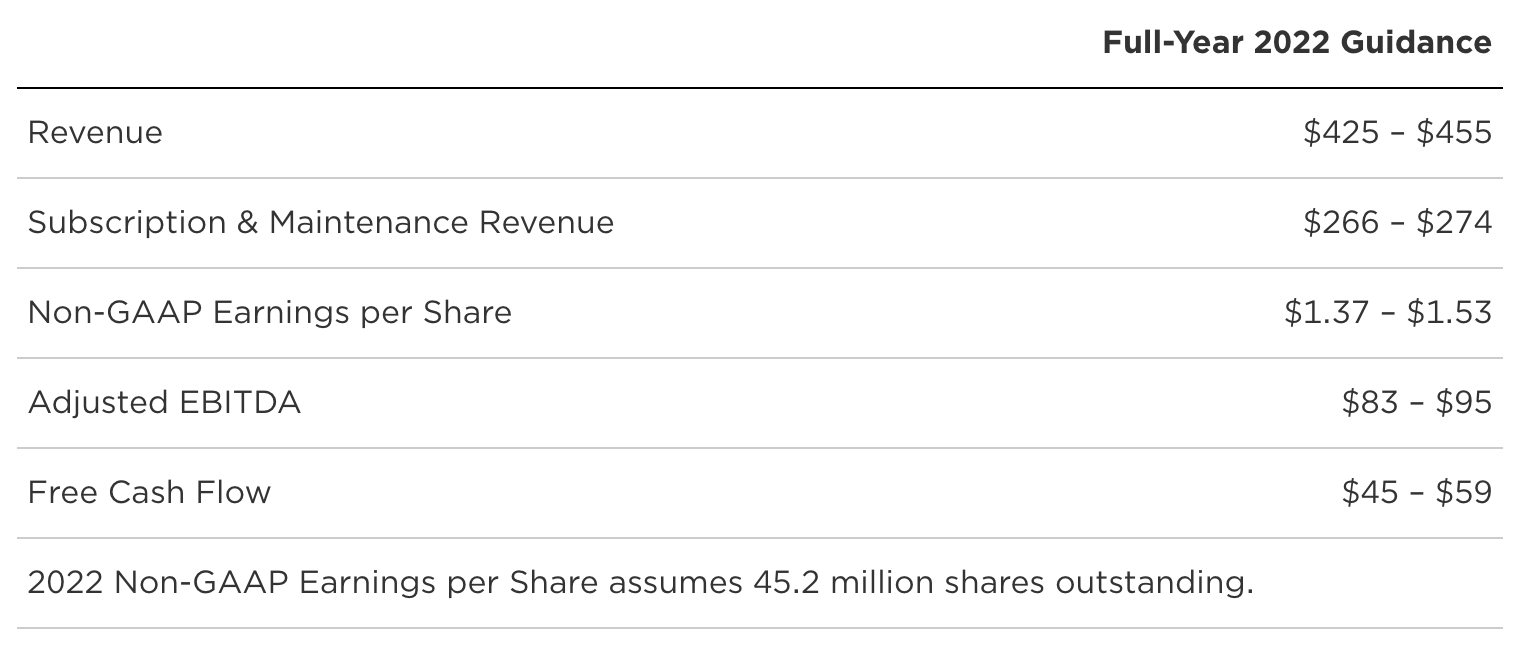
When it comes to the 2022 fiscal year as a whole, management expects revenue to come in at between $425 million and $455 million. At the midpoint, that would translate to a year-over-year growth rate of 7.3%. So far, the company is already on track for that. In the first half of the year, sales came in at $198.3 million. That’s 4.8% above the $189.2 million generated the same time last year. What this does imply, however, is that the second half of the year must be stronger than the first half. Regardless of what the outcome is, it is also clear that the fastest growing portion of the company and, in fact, the only growing part this year, relates to the subscriptions. Subscription revenue in the first half of the year came in strong at $67.1 million. That represents an increase of 44.7% over the $46.4 million generated just one year earlier. Maintenance revenue, on the other hand, dropped by 7%, while perpetual licenses declined by 38.5%. Integrated solutions revenue inched down by 2.3%, and professional services and training revenue declined by 9.5%.
Avid Technology
Avid Technology
On the bottom line, management anticipates earnings per share of between $1.37 and $1.53. At the midpoint, this would translate to net income of $65.5 million. Meanwhile, EBITDA should come in at between $83 million and $95 million, with a midpoint reading of $89 million. No guidance was given when it came to operating cash flow. But if we assume that it will increase at the same rate that EBITDA should, then we should anticipate a reading this year of $73.7 million. Using these figures, we can see that the company is trading at a forward price-to-earnings multiple of 18.7. This is down from the 29.5 reading we get using 2021’s results. The price to operating cash flow multiple should drop from 19.6 to 16.6, while the EV to EBITDA multiple should decline from 18 to 15.3.

Author – SEC EDGAR Data
Author – SEC EDGAR Data
Normally, when I perform an analysis of a company, I really like to compare that firm to similar businesses. However, I could not really find any good comparable businesses. Even the ones that operate in the same sector seem to generate a significant portion of their revenue from hardware while it’s clear that Avid Technology is focused much more on software and, in particular, subscriptions. What I can say is that, in general, these trading multiples are not particularly high, nor are they particularly low. They would normally indicate a company that is trading at or around fair value. And that’s especially true if the company in question has a history of growing its profitability.
What makes me bullish about the company are two things. In the short term, the company might benefit further from the announcement that it will be joining the S&P SmallCap 600 listing on September 1st. Not only does this bring the company onto the radar of additional investors; it has the benefit of being in a position that some index funds and mutual funds will either have to or be pressured to acquire the stock to add to their holdings. Already, that announcement sent shares up 12% on August 30th. In the long term, we have the benefit that the enterprise continues to grow a high margin portion of itself. This means that the company is transforming in a positive way and, while revenue has been affected by the declines across other categories, this transition is already proving beneficial from a cash flow perspective and, eventually, will prove beneficial from a revenue perspective.
Based on the data provided, I will say that I am definitely encouraged by what I’m seeing with Avid Technology. Although the company has had a bumpy operating history from a revenue perspective, cash flows are promising and net profits are as well. Shares are not trading at levels that I would consider to be unreasonable. If anything, the company seems to offer additional upside potential for investors. Because of this, I’ve decided to rate the enterprise a soft ‘buy’ at this time.
Crude Value Insights offers you an investing service and community focused on oil and natural gas. We focus on cash flow and the companies that generate it, leading to value and growth prospects with real potential.
Subscribers get to use a 50+ stock model account, in-depth cash flow analyses of E&P firms, and live chat discussion of the sector.
Sign up today for your two-week free trial and get a new lease on oil & gas!
This article was written by
Daniel is currently the manager of Avaring Capital Advisors, LLC, a registered investment advisor that oversees one hedge fund, and he runs Crude Value Insights, a value-oriented newsletter aimed at analyzing the cash flows and assessing the value of companies in the oil and gas space. His primary focus is on finding businesses that are trading at a significant discount to their intrinsic value by employing a combination of Benjamin Graham’s investment philosophy and a contrarian approach to the market and the securities therein.
Disclosure: I/we have no stock, option or similar derivative position in any of the companies mentioned, and no plans to initiate any such positions within the next 72 hours. I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.